Nvidia, six months on: thesis intact, price less so
The March thesis has played out faster than I expected. Guidance was raised twice, margins held, and the stock is up about 45%. The question now is not the business but the price, and I'm trimming into strength.
Follows up on: Nvidia: the data-center cycle has another leg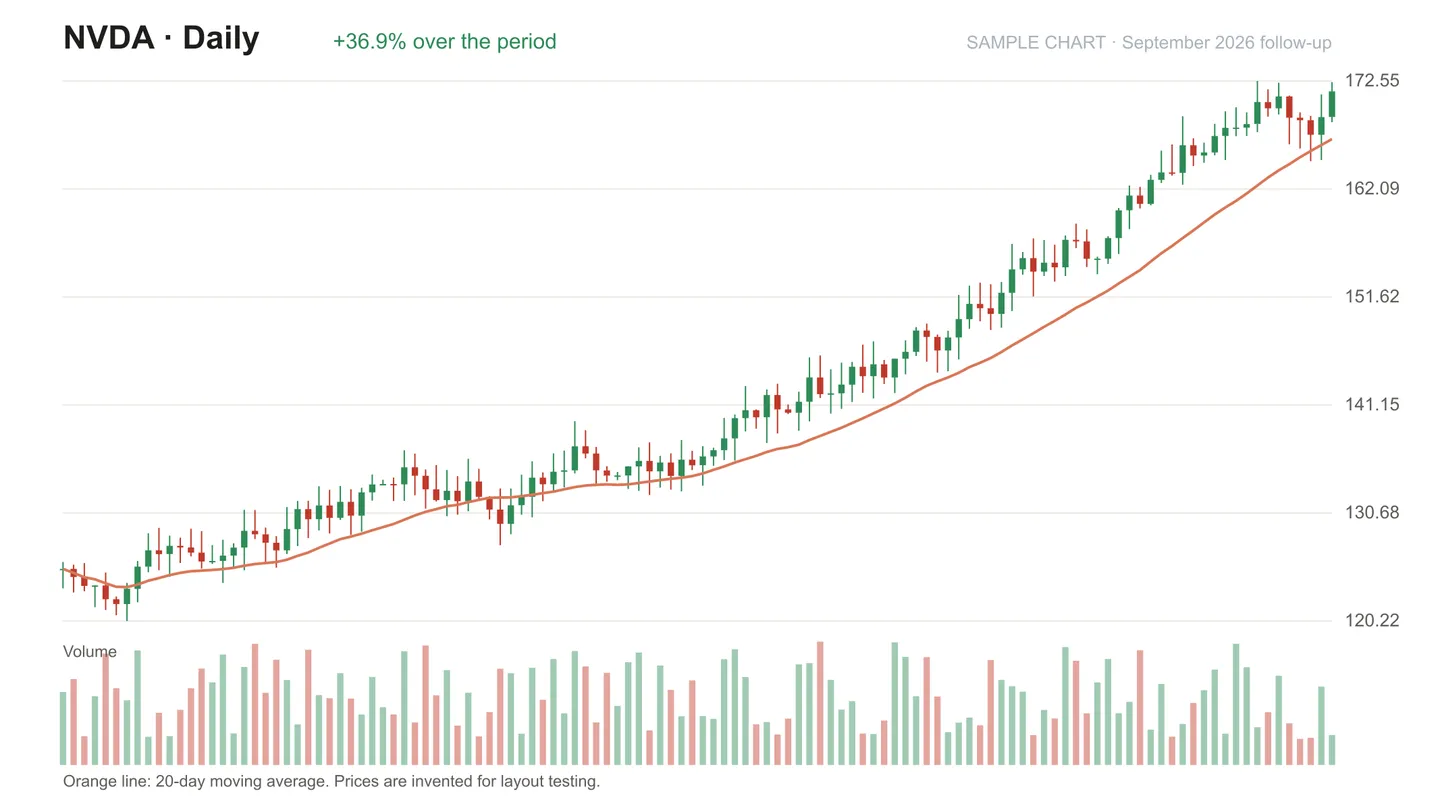
Sample research report used to test the layout. Delete before launch.
What changed since the last report
Almost everything went the right way. Guidance was raised in both quarters since March, gross margin stayed in the mid-seventies, and the second tier of cloud providers did start ordering at scale. The stock is up roughly 45% from the March report.
Thesis
Unchanged on the business. The cycle still looks young. What changed is the price: at this level the stock discounts most of next year’s upside, and the setup into earnings is crowded.
Catalysts
- Earnings on Wednesday. A raise is expected, so the bar is high.
- Product ramp commentary for the fourth quarter.
- The bar is too high in term of growth
Risks
Same list as March, plus one: expectations. When every preview note agrees, the reaction to a merely good quarter tends to be down.
What would prove me wrong
On the bearish side of this update: a guide that clears the highest estimate with margin to spare. Then the stock is not expensive, and I would regret trimming.
Position
Trimming a third of the position here and keeping the rest with a stop under the early-September gap. I would rebuild on a pullback toward the 50-day average if the report is clean.