Nvidia: the data-center cycle has another leg
My initial thesis on Nvidia: the data-center build-out is earlier in its cycle than the bears think, gross margin has a floor the market is not pricing, and the stock is cheap on next year's numbers if the guidance holds.
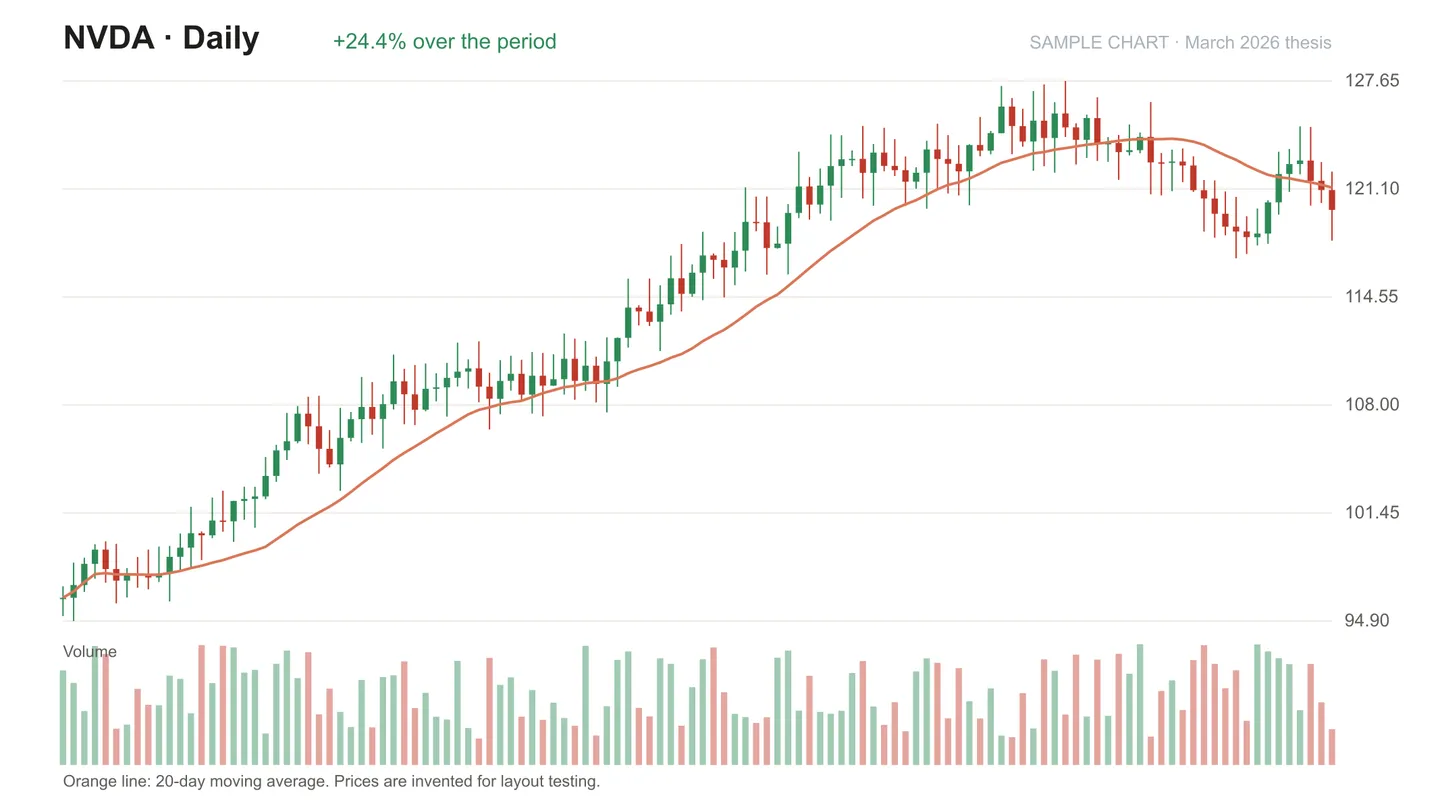
Sample research report used to test the layout. Delete before launch.
Thesis
The market treats Nvidia as a cyclical at the top of its cycle. I think the cycle is younger than that: hyperscaler capital-expenditure guidance for this year is up again, the customer list is broadening beyond the four largest buyers, and the software side of the business is starting to show up in the numbers.
Catalysts
- Next quarter’s guidance, which I expect to be raised on data-center demand.
- The new product family shipping in volume in the second half.
- Any sign that the second tier of cloud providers is ordering at scale.
Risks
- Customer concentration: four buyers still make up most of the revenue.
- Export restrictions, which can change the addressable market overnight.
- A capex pause at any large customer, even a temporary one, would hit the stock hard.
What would prove me wrong
Gross margin guidance falling below the mid-seventies for two quarters in a row. That would say pricing power is gone, and my whole thesis rests on it.
Position
Starting a half-size position here, with the rest added on either a pullback to the 200-day average or a clean break above the winter high.