Apple: services are the story, hardware is the noise
Apple's services segment now earns more gross profit than the iPhone, grows at double digits, and gets no separate credit in the multiple. The base the stock has been building since June looks like accumulation to me.
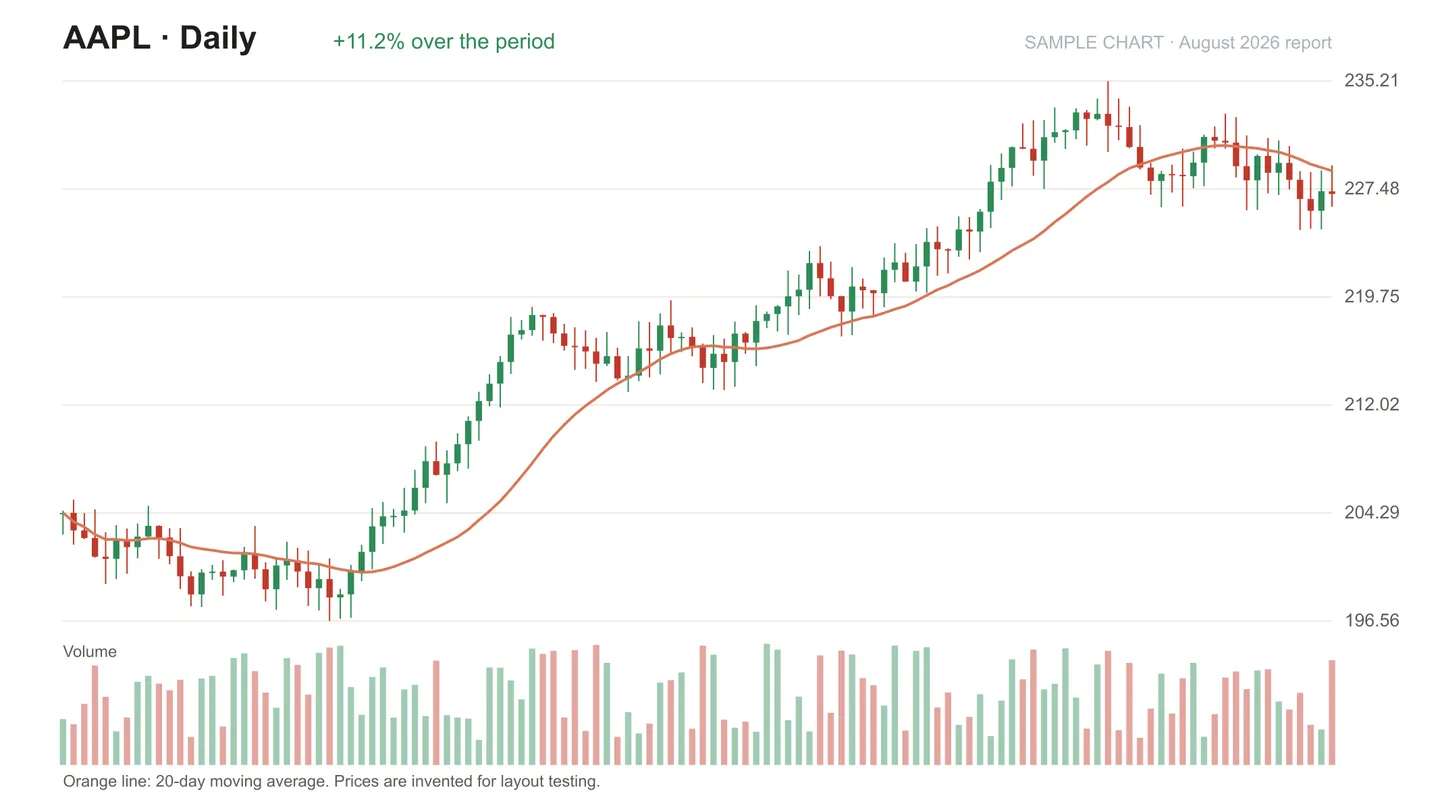
Sample research report used to test the layout. Delete before launch.
Thesis
Every quarter the headlines are about iPhone units, and every quarter services grows double digits with margins above seventy percent. Services now contributes more gross profit than the phone. At some point the multiple has to reflect that mix, and I think the current base is where it starts.
Catalysts
- The September product event, which usually marks the low point of sentiment for the year.
- Services pricing changes announced this summer, which flow through from the fourth quarter.
- Buyback pace, which has been the quiet support under every pullback.
Risks
- Regulatory pressure on the app store commission structure in Europe and the United States.
- A weak upgrade cycle, which would keep the story stuck on hardware.
- China demand is weak.
What would prove me wrong
Services growth slowing into single digits for two quarters. The mix argument only works if that segment keeps compounding.
Position
Building a position inside the base, with a stop under the June low. A breakout above the range high would be the signal to add.